Defence and Deeptech lead Baltic funding as pre-seed surge offsets growth capital drought
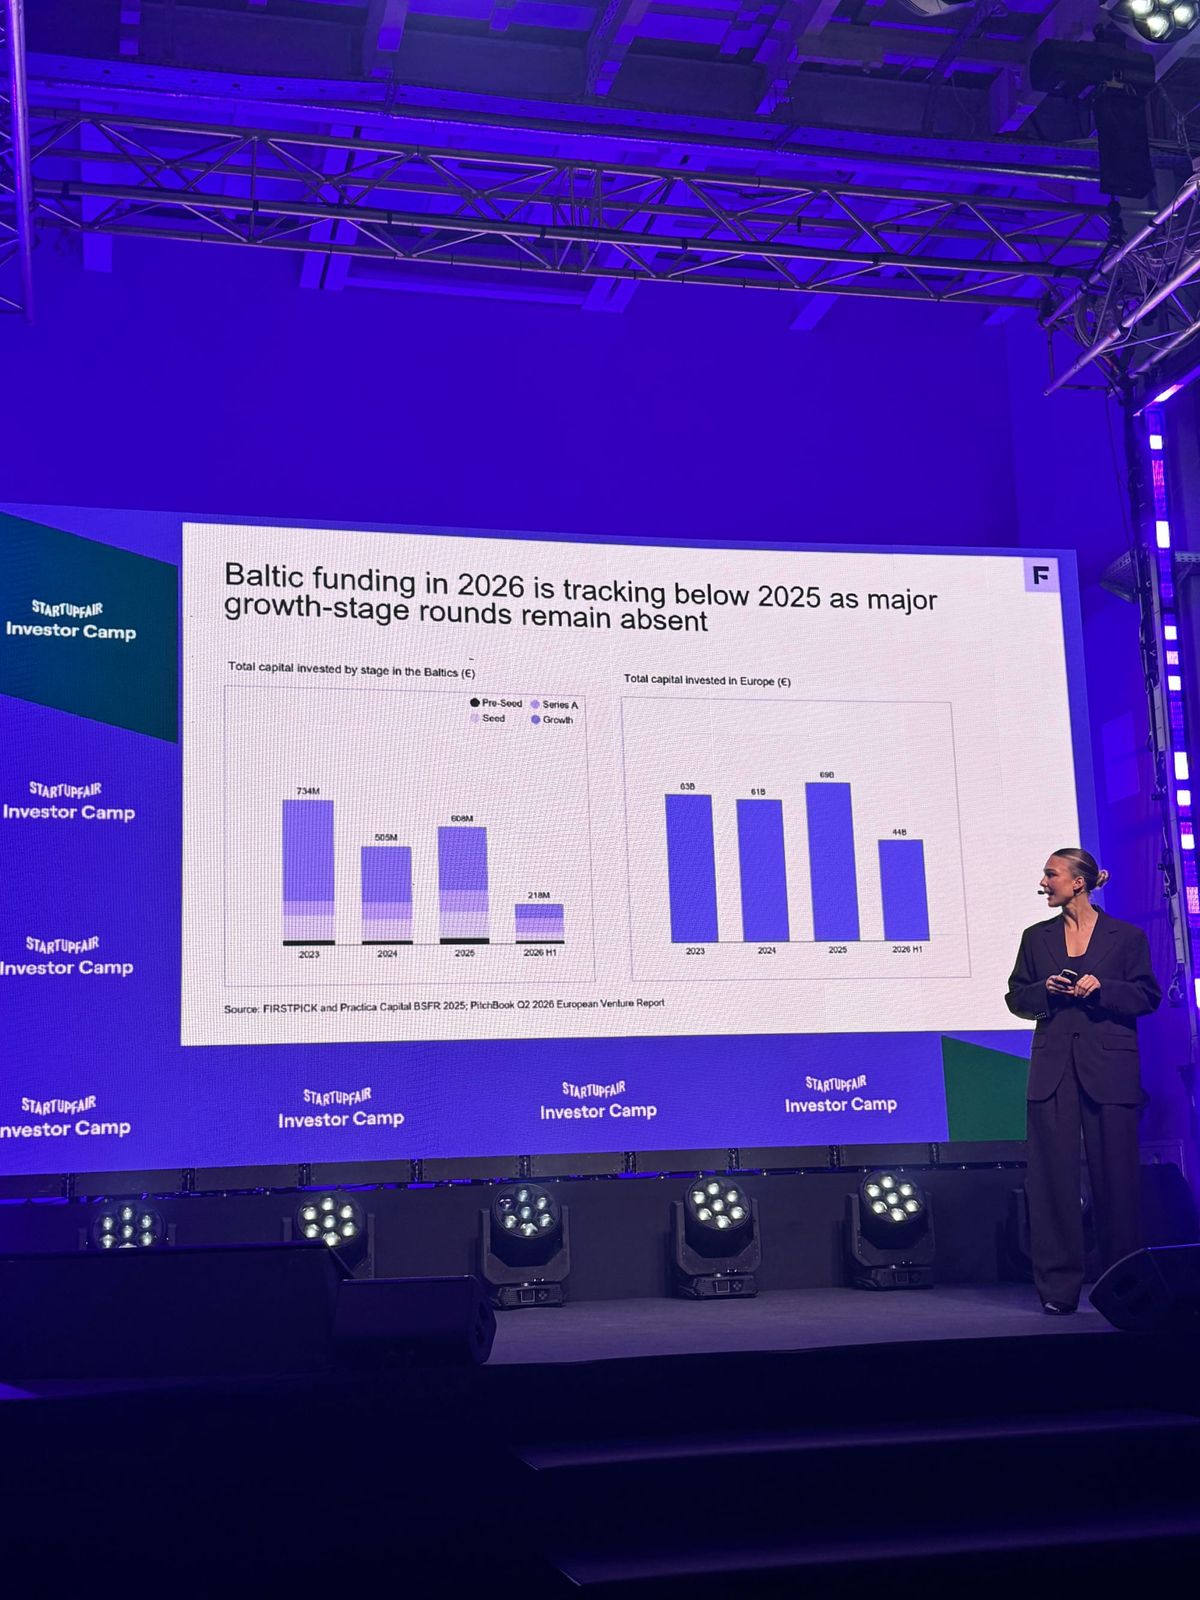
VILNIUS — The Baltic startup ecosystem is experiencing a structural realignment in 2026: while growth-stage venture capital has contracted, early-stage activity is undergoing a renaissance driven by defence technology, deeptech, and an influx of pre-seed initiatives.
Data presented at StartupFair shows regional funding standing at €353 million year-to-date, trailing significantly 2025’s full-year total of €608 million. The pull-back is concentrated primarily in growth-stage rounds, which remain scarce across the Baltic states.
Defence and Deeptech Outpace Traditional Verticals
Despite macro headwinds, capital allocation has concentrated heavily into security and deep technology:
- Defence leads capital volume: Defence startups secured the highest total funding, capturing €39 million across five rounds.
- Deeptech secures second place: Deeptech companies raised €38 million across four deals, establishing hard tech as a priority for institutional investors.
- AI dominates deal count: Artificial intelligence generated the highest transaction volume with 14 completed rounds, though totalling €22 million in capital raised.
Social commerce (€22 million) and food tech (€20 million) rounded out the top five funded sectors by capital volume.
 Tarmo Virki
Pre-Seed Surge Driven by Community Initiatives
At the foundational stage, the region is seeing renewed momentum driven by founder-led initiatives such as hacker houses designed to feed early deal flow:
- Rising median round sizes: The median Baltic pre-seed round reached €409,000 in 2026, a 3.1x increase from €132,000 in 2020.
- Blurring boundary with Seed: In H1 2026, 33% of pre-seed rounds exceeded €1 million, up from 16% in 2025.
- Capital acceleration: Pre-seed funding reached €30 million in H1 2026, representing 64% of the total capital raised in pre-seed throughout 2025.
Outlier transactions — such as Zobi’s €5 million pre-seed round in August 2026 —demonstrate that high-conviction teams are commanding larger valuations at earlier stages.
Seed Stage Experiences Mid-Market Squeeze
In contrast to the pre-seed momentum, Seed-stage venture activity experienced a broad pullback across key metrics:
- Capital reduction: Total Seed capital dropped to €48 million in H1 2026, down from €132 million in 2025.
- Fewer completed transactions: Only 23 Seed deals closed in H1 2026, falling below the 2023–2025 historical baseline.
- Lower median checks: Median Seed rounds decreased to €1.8 million in H1 2026 from €2 million in 2025.
Active regional funds — led by FIRSTPICK, Practica Capital, and Coinvest Capital, each completing five or more deals in H1 — are relying on pre-seed pipeline initiatives to reactivate Seed-stage deal flow in upcoming quarters.

Comments ()